
I’ll add a caveat to this series of articles. I’m not an economist. I’m a philosopher with a special interest in Daoism who believes he has a talent for explaining complex issues to the general public. I do this because I think a lot of the news that people get from the legacy media, social media ‘influencers’, and political parties is based on misconceptions and delusional thinking. That’s the point of Hulet’s Backgrounder. My understanding of Modern Monetary Theory (MMT) is based mostly on two sources: L. Randall Wray’s video Modern Monetary Theory for Beginners and The Deficit Myth by Stephanie Kelton. WDH]
In my last article in this series, I talked about exactly what money is and how it was created. I pointed-out that it appears that mostly it came about because a sovereign did two things: create a currency that he forced people to accept for goods and services—and then levied taxes that could be paid with it. I also showed evidence that this continues to this day, only the money that’s created is mostly in the form of bits and bites on a computer in the Bank of Canada/Federal Reserve that flow through a series of intermediary banking systems. In this article I’m trying to explain what I think MMT believes a country’s deficit really is—and why it shouldn’t always be something people fear.
What Exactly Does Money Do?
I talked about where money comes from in the last article and in this one I’m going to suggest what money does. Of course, all people know that money makes it easier to buy and sell. That’s the individual person’s experience, but what does it do in terms of the big picture?
When it’s managed properly, money helps mobilize economic activity. To illustrate what I mean, let me create a hypothetical example. I have a group of people who use a currency to exchange goods and services. Let’s consider a group of 100 people with a total of $1,000 worth of currency. Let’s also say that this money starts out being equally distributed—everyone has 10 dollars. Those 100 people can use that money to buy from one another. A lot of different things are going to happen. Some of them are going to end up with more than $10 and some are going to end up with nothing at all. (Let’s ignore that for now—I’ll get back to it.)
Assume that this tiny little economy is functioning more-or-less OK, but then think about what would happen if the number of people grow and/or the amount of economic activity the group does gets bigger. In other words, the tiny hypothetical economy is expanding. If the amount of money in the system still stays at $1000, it’s going to cause problems because the relative value of the money to buy all the goods and services is going to go up as the tiny economy grows—simply because there are more things to buy but the same amount of money is still in the system.
When that happens, the conventional wisdom is to hold onto your money because it keeps growing in value. No one buys anything today for $10 when they know it will only cost $9 next week. And no one is going to make risky or cheap loans if they know that their savings are going to grow in value just sitting in the banks (or even under their mattress). This phenomenon is called ‘deflation’—and it was what caused total havoc to the economies of the world during the Great Depression.
So what’s the solution? The government needs to create more money as the economy grows. If the population increases, the national bank will have to dump another $10 per new person into the economy to keep things steady. Also, if people start increasing the value of the goods and services in the community by finding more efficient ways to do things, then the banker will have to inject some currency into the system to stop the money from deflating.
So how does a government increase the money supply?
It does it by running a deficit. That is to say, the government decides to do something—build a bridge or hydroelectric dam, create a new program like a child tax credit, etc—and pays for it by creating new currency. That’s pretty much what Canada, the US, Japan, etc, are doing when they run up a deficit. A deficit in a national budget is a measure of how much the government has increased the money supply that year. And the national ‘debt’ is a measure of how much the government has increased the money supply over a given period of time.
If this is so, then why are so many people constantly banging the drum about deficits? Here’s another clip from the L. Randall Wray video I quoted in my previous article on this subject. I think it suggests a reason why.
Here’s a link to the Wikipedia article about Paul Samuelson. I’d never heard of him before, but he was a very well-regarded economist! (He won the first so-called ‘Nobel Prize’ in economics—among other things.) And here’s what I assume to be the video clip that Wray mentions.
If we look at the nations of the world right now, I’d suggest that the ‘old tyme religion’ of economics has stopped scaring governments into avoiding deficit spending.
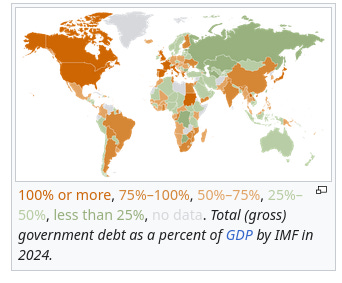
According to the above map, Canada, the United States, Japan, and Great Britain have national debts (ie: have created extra currency for their economy) that amounts to over 100% of the Gross Domestic Profit (GDP). Following behind them, are India, China, and Brazil, which had deficits of between 75 and 100%. (I’m not going to talk about Eurozone for reasons that will become obvious later one.) It looks to this lay person, therefore, that Dr. Samuelson’s nightmare future has arrived—increasingly, politicians around the world have begun to believe ‘deficits don’t matter’.
Is this true? I’d say yes and no. If people believe deficits really are inherently destructive—and for the reasons usually stated—I’d suggest in rebuttal by talking about the massive growth in wealth that has occurred at the same time that the consensus about balance budgets has begun to fall apart. Take a look at the following three-dimensional (X, Y, plus time lapse) graph that shows the growth of government spending over time. It comes from an article titled Historical poverty reductions: more than a story about “free-market capitalism” (Pay attention to the two huge spikes during WWI and WWII—and the higher ‘new normal’ that arrives with the 1960s.)
And in the following graph from the same paper the researcher has parsed out the amount of government spending/year/country that is specifically aimed a social programs like old age security, subsidies for the disabled, unemployment insurance, etc. (That’s why it shows no spike in activity during the two world wars.)
Yes, governments have expanded money supply a lot starting in the late 1950s and carrying on to today. As Samuelson would say, 19th century politicians like Gladstone would be rolling in their graves to see how willing modern governments are to increase their currency (aka ‘running up deficits’). The thing to remember, though, is during this time of easy access to currency the people of these nations have found their standards of living increasing in ways that were unheard of by previous generations. Here’s an easy-to-understand graph I found at a blog that shows long-term economic growth in both the USA and Canada.
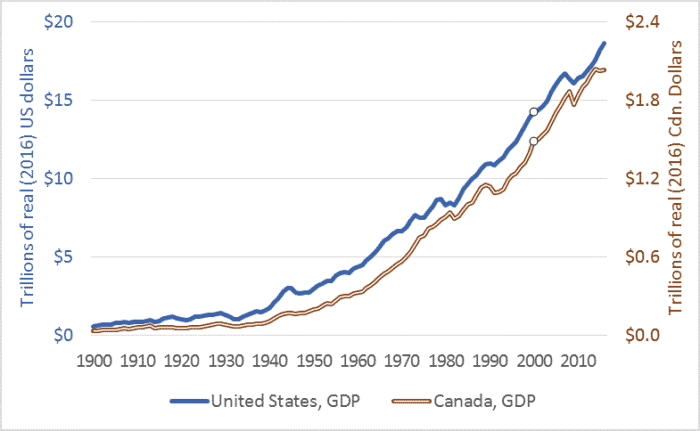
Again, note the time where things really kicked into ‘over drive’—the late 1950s and early 1960s.
If Deficits Don’t Count, Why Do We Have Taxes?
If the evidence seems to be overwhelming that running up pretty hefty deficits not only doesn’t hurt the economy—but actually helps it—why bother with things like taxes and spending cuts? Couldn’t a government pay for everything with deficits?
No. That’s because there are real limits on how much money an economy needs. It’s sorta like Goldie Locks and the three bears. If you don’t have enough money for the economy—it encourages stagnation and deflation. If you put too much into it, you get inflation and people’s incomes erode. (There are other causes of inflation—which we saw after COVID and now during the latest Gulf War—but that’s another story.)
Lets go back to my hypothetical mini-economy of 100 people and $1000 dollars between them. What happens if the sovereign bank doubles the amount of money people have overnight? If lack of money is all that’s been stopping a business from building a new machine that can double the number of shoes it can make, and they can find workers, and there’s a demand for more shoes—the money could end up helping the economy grow and cut the cost of living. But if instead there were enough shoes to go around, and everyone already had a job, and there was nothing else that needed doing, then the extra money would just lead to a bidding war for both products and workers. And that would cause inflation.
Another problem that societies can face (and we are right now) is money can get ‘trapped’ in the hands of a small number of super-wealthy individuals. These are the people I tend to call ‘bond villains’—Elon Musk, Mark Zuckerberg, Bill Gates, etc. All the extra money they have damages society. By that I mean these individuals start having far, far too much influence on society. Because they can dump huge amounts of money into the electoral process, hire armies of lobbyists, create 3rd-party political advertising, pay for so-called ‘think tanks’, etc, their wishes often over-ride what’s best for the majority of citizens.
A well-run government pays more attention to these two issues—inflation and wealth stratification—than they do the mere size of the deficit. And the way to control both problems are changes to the tax codes.
In the case of inflation, the government wants to cut down the pool of money in the hands of middle-income people. That’s because there’s a lot more of them than the wealthy, and they tend to spend their money instead of just investing it (or hide it in a tax haven).
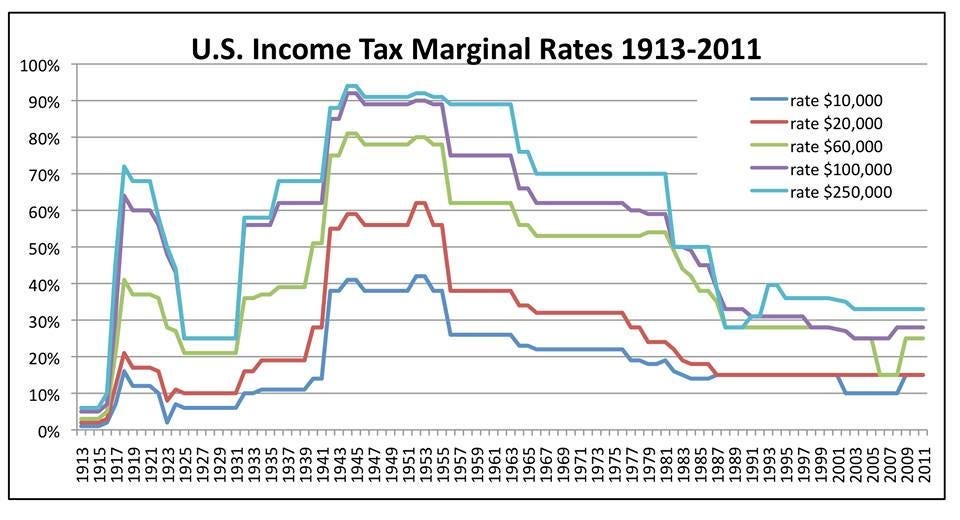
With regard to wealth stratification, the government needs to pull money from the very wealthy in order to reduce their ability to manipulate government and society. This is not an impossible task, as it has been done in the past by using a mix of very high tax brackets plus an inheritance tax to stop families from moving wealth from generation to generation. Take a look at the income tax rates that existed over time in the USA. As you can see, from 1941 to 1965 there was a tax rate of around 90% levied against individual annual incomes over a quarter million dollars. And since then the rates have declined dramatically to today where they are a little over 30%.
At the same time, the estate tax has become increasingly meaningless in both Canada and the USA as various exemptions and ‘work arounds’ have it pretty much useless as a mechanism for redistributing wealth from the rich to the poor.
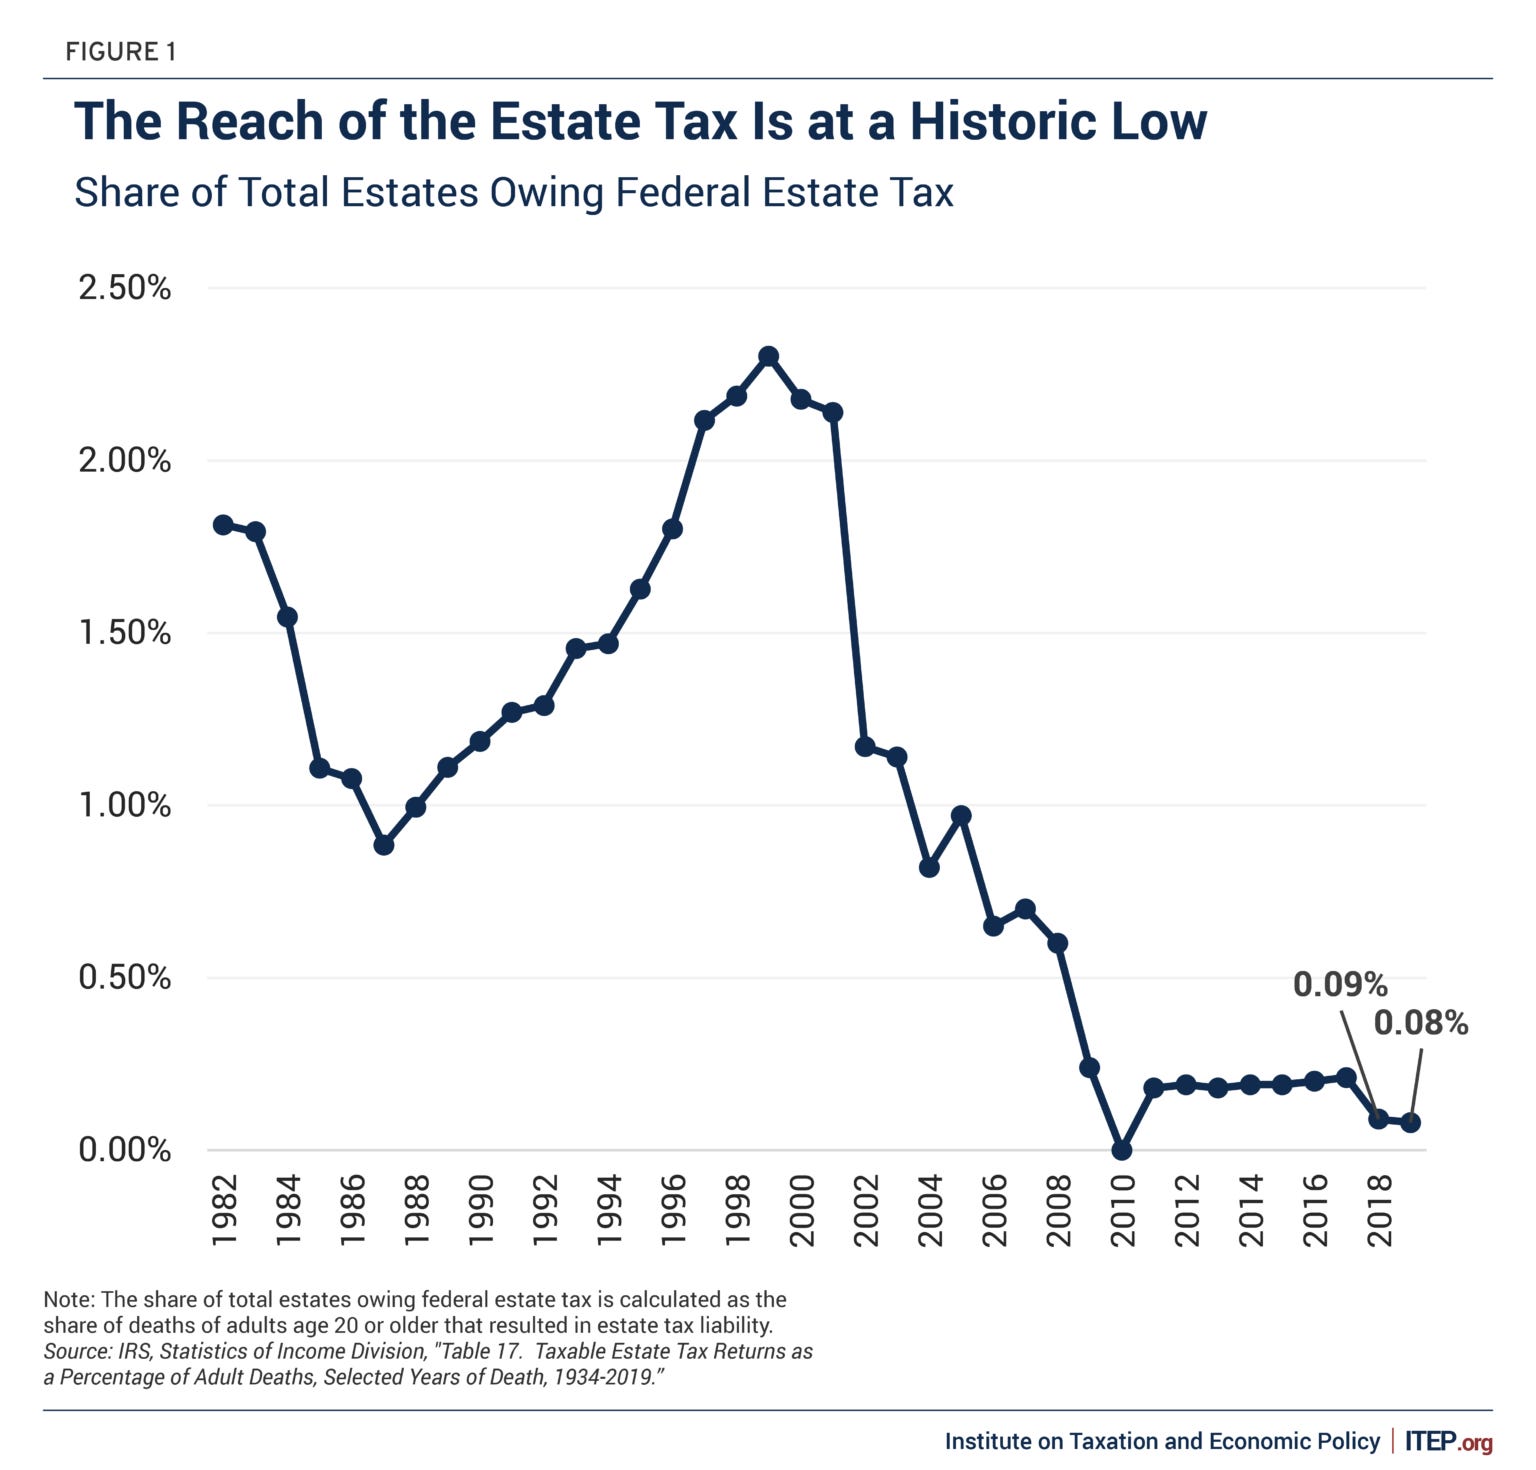
So taxation is tremendously important to governments. It shouldn’t be used to pay for everything—sometimes deficits are called for. But it can be used to reign in inflation and also to prevent unhealthy wealth stratification that will threaten the existence of democratic governance.
One of the reasons why I think it’s so important to discuss what Modern Monetary Theory (MMT) has to say is fixating on deficit spending as something inherently bad diverts attention from the terrible problems we have created by refusing to use the taxation tool in a way that would benefit society-as-a-whole instead of a small number of people who already have far, far, too much wealth and influence.
Important Points to Understand
Only Governments With Their Own Currency Benefit from MMT
There are a couple of important caveats that people need to understand about MMT. The first one is only federal governments that issue their nation’s own currency can use deficits to manage their economy. That means municipal and provincial/state governments cannot help their citizens through deficit spending. It might be that the federal government will create programs that help lower levels of government and finances them through creating more currency. But the upper level of government makes the decision, not the lower one.
The second point to understand is not all countries actually have the ability to create currency to help their economies. Some people might thinking about Greece, which had a problem with deficits a few years back. The thing to remember is Greece does not control it’s own currency—it’s more of a province of the European Union than an independent state. They use the Euro, not their old currency, the Drachma.
There are other nations of the world—for example Equador and El Salvador—that have adopted the US dollar as their domestic currency. This means that they also cannot create more money to help their economy grow.
But What About Weimar Germany?
Everyone’s heard of the German hyperinflation of the early 1920s. At one time, a loaf of bread cost 200 billion marks by the end of 1923. What they generally don’t know was that this was the result of the treaty that ended WWI which required the new German government to pay astronomical war reparations to the Allied victors.
What it did was require huge payments in both currency and kind (coal, for example). According to historians, the people running the government encouraged hyperinflation so the country could pay off big chunks of the debt with worthless money.
British and French experts stated that this was in an effort to ruin the German currency and, as well as escaping the need for budgetary reform, avoid paying reparations altogether, a claim supported by Reich Chancellery records showing that delaying the currency and budgetary reform that could have addressed hyperinflation was seen as advantageous. Whilst ruinous to the economy and politically destabilising, hyperinflation had advantageous aspects for the German government as, although the war reparations were not listed in paper currency, domestic debts owed from the war were listed, meaning that inflation greatly reduced this debt relative to revenues.[5]: 239
At the same time, France occupied the Ruhr Valley in order to force Germany to pay the in-kind reparations they felt they deserved. (German troops had occupied and destroyed large parts of French industry, whereas most German factories and mines emerged unscathed by war’s end.) The occupation was met with resistance by workers, which also lowered productivity.
Because of this decline in industrial capacity (let’s also not forget the decline in skilled workers because of war casualties), the actual economy shrank—which meant that there was too much money sloshing around. The cherry on the top of this sh*t Sunday was the old Imperial government had decided to fund the war exclusively by deficit—which meant that even before the victors decided to bleed Germany dry, it had far, far too much money already in the system.
In other words, German hyperinflation of the 1920s was an extremely bizarre exception caused by unique events that has no bearing on a modern, moderately well-governed nation.
This probably more than enough for one article, so I’m going to stop here. In my next in the series I hope to talk a bit about the policy implications of MMT.